
HELOC in Canada: The 65% Rule, Limits and Payments
How much a Canadian HELOC lets you borrow under the 65% and 20% equity rules, what interest-only payments cost, and how the stress test and rate rises change it.
By Redbison Dev · · 9 min read
Canada edition. Canadian edition in CA$, built on FCAC's HELOC rules (65% of home value, 20% equity when combined with a mortgage), OSFI Guideline B-20, the mortgage stress test and the Bank of Canada's policy rate. US edition
In Canada a home equity line of credit can be at most 65% of your home's value, and if it sits alongside your mortgage you must keep at least 20% equity. So on a CA$900,000 home with CA$400,000 left on the mortgage, the most you can have on the line is CA$320,000: 80% of the value is CA$720,000, minus the mortgage. If the mortgage were down to CA$100,000, the 20% equity rule would allow CA$620,000, but the line stops at CA$585,000, which is 65% of the value. Most Canadian HELOCs are variable and allow interest-only payments, which keeps the monthly cost low and the debt exactly where it started.
This edition works through the limits and costs with the Home Equity Line of Credit Calculator for Canada. It explains the arithmetic, not whether borrowing against your home is right for you; a fee-only adviser or your lender can test it against your own budget.
The two limits, and which one binds
The Financial Consumer Agency of Canada's HELOC page sets out the rules a consumer sees:
- You may borrow up to 65% of your home's value on a HELOC.
- A standalone HELOC needs more than 35% equity.
- A HELOC combined with a mortgage needs 20% equity.
Behind the 65% figure is OSFI's Guideline B-20 for federally regulated lenders, which caps the non-amortizing, revolving part of a HELOC at a loan-to-value ratio of 65% or less. Lenders can lend more against the home, but B-20 says the part above 65% should be amortized, repaid with principal and interest like a mortgage.
The calculator takes the home value, mortgage balance, an 80% combined limit (20% equity) and the 65% line cap, and reports the smaller of the two:
| Home value | Mortgage | Room at 80% combined | 65% line cap | Maximum line |
|---|---|---|---|---|
| CA$900,000 | CA$400,000 | CA$320,000 | CA$585,000 | CA$320,000 |
| CA$900,000 | CA$300,000 | CA$420,000 | CA$585,000 | CA$420,000 |
| CA$900,000 | CA$100,000 | CA$620,000 | CA$585,000 | CA$585,000 |
| CA$750,000 | none | CA$600,000 | CA$487,500 | CA$487,500 |
With a large mortgage, the 20% equity rule binds. Once the mortgage is small, the 65% cap does.
Readvanceable mortgages: room that grows back
FCAC explains that a HELOC combined with a mortgage must be with the same lender, and that the available credit rises as you pay down the mortgage principal; it is sometimes called a readvanceable mortgage. In the table, paying the mortgage from CA$400,000 to CA$300,000 adds CA$100,000 of room on the line.
That is convenient and also the main trap. Every dollar of principal you repay becomes a dollar you can borrow again, so the total debt against the home need not fall for years. Decide what the line is for before you open it. A standalone HELOC, by contrast, can be with a different lender and does not grow when you pay the mortgage down.
A worked example: CA$80,000 for a renovation
Enter the calculator's defaults: home CA$900,000, mortgage CA$400,000, 80% combined, 65% cap, draw CA$80,000 at an example variable rate of 5.45%.
- Maximum line: CA$320,000. Combined debt after the draw: 53.3% of the home's value.
- Interest-only payment: CA$80,000 x 5.45% / 12 = CA$363.33 a month.
- If the rate rises 2 points: CA$496.67 a month.
- To clear the CA$80,000 over 15 years instead: CA$651.55 a month.
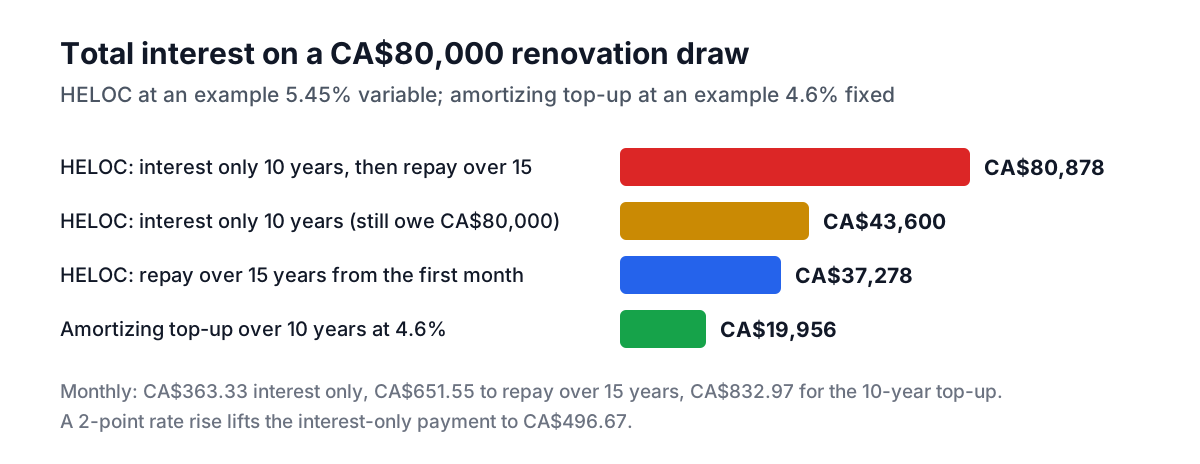
Now look at the total cost of each way of paying, because this is where interest-only quietly costs most:
| Approach | Monthly | Total interest |
|---|---|---|
| Interest only for 10 years | CA$363.33 | CA$43,600, and you still owe CA$80,000 |
| Then repaid over 15 years | CA$651.55 | CA$80,878 in all |
| Repaid over 15 years from the first month | CA$651.55 | CA$37,278 |
| Amortizing top-up, 10 years at an example 4.6% | CA$832.97 | CA$19,956 |
Ten years of minimum payments costs CA$43,600 and leaves the full balance in place. Paying principal from the start costs CA$288 a month more but halves the lifetime interest. FCAC's own warning is plain: interest-only payments won't pay off the loan.
Rates, prime and the Bank of Canada
FCAC notes that most HELOCs are variable, usually set at the lender's prime rate plus a margin; its example is prime plus 1%. Your lender may change the rate at any time and must notify you in writing within 30 days. Lenders set their own prime rates; the backdrop is the Bank of Canada's policy rate, which was raised by 25 basis points to 2.50% on October 28, 2026, with the next decision scheduled for December 9, 2026.
The 5.45% in the example is an illustration, not a quote. Use your lender's offer, then run the calculator's rate-rise row, because a variable line moves your payment the month prime moves. On the CA$80,000 draw, each percentage point is about CA$67 a month on interest-only payments.
The stress test applies to a HELOC too
FCAC's page on preparing for a mortgage says that if you already have a mortgage, you must pass the stress test to take out a HELOC or refinance. Banks qualify you at the higher of 5.25% or your contract rate plus 2%. OSFI's minimum qualifying rate page states the same rule for uninsured mortgages.
At an example contract rate of 5.45%, the qualifying rate is 7.45%, and the interest-only payment on CA$80,000 at that rate is CA$496.67, the same as the calculator's 2-point rate-rise row. If your budget cannot carry that figure, the lender is unlikely to approve the line.
HELOC or refinance?
A refinance adds the money to your mortgage as an amortizing loan, fixed or variable, often at a lower rate than a HELOC, but breaking a fixed mortgage term early can trigger a prepayment penalty. A HELOC avoids that penalty and charges interest only on what you draw. Rough rule from the example: if you will draw the whole amount at once and repay it on a schedule, the amortizing option costs less; if you need money in stages, or only for a short time, the line's flexibility can be worth its higher rate. Compare both with the Refinance Calculator for Canada.
FCAC also lists the costs of setting a HELOC up: appraisal fees, legal fees to register the home as collateral, title search fees, possible administration and monthly fees, and discharge fees when you close it.
Tools for this job
- Home Equity Line of Credit Calculator for Canada: maximum line under the 65% and 80% limits, interest-only and repayment payments, and a rate-rise test.
- Refinance Calculator for Canada: the cost of breaking your mortgage to borrow against the home instead.
- Mortgage Calculator for Canada: how fast the mortgage, and so the readvanceable room, changes.
- Net Worth Calculator for Canada: home equity in the context of your other assets and debts.
- Related reading: how mortgages work in Canada, and the US HELOC guide for US draw and repayment periods.
Frequently asked questions
How much can I borrow on a HELOC in Canada?
Up to 65% of your home's value on the line itself, and no more than leaves you 20% equity once your mortgage is counted. On a CA$900,000 home with a CA$400,000 mortgage that is CA$320,000; with a CA$100,000 mortgage, the 65% cap of CA$585,000 binds.
Do I have to pay principal on a Canadian HELOC?
Often not. FCAC says minimum payments may be interest only, or part principal and interest. Interest only keeps the payment low but never reduces the debt: CA$80,000 at 5.45% costs CA$363.33 a month and CA$43,600 over ten years, with the full CA$80,000 still owing.
Do I need to pass the stress test for a HELOC?
Yes, at a bank. FCAC says existing homeowners must pass the stress test to take out a HELOC. You qualify at the higher of 5.25% or your contract rate plus 2%, so a 5.45% line is tested at 7.45%.
What happens to my HELOC if rates go up?
Your payment rises as soon as the lender changes the rate; it must tell you in writing within 30 days. On a CA$80,000 interest-only balance, each percentage point adds about CA$67 a month, and a 2-point rise takes the payment from CA$363.33 to CA$496.67.
Sources and further reading
- Home equity line of credit, Financial Consumer Agency of Canada. The 65% limit, 35% and 20% equity rules, readvanceable mortgages, variable rates, interest-only payments, fees and risks.
- Residential Mortgage Underwriting Practices and Procedures, Guideline B-20 (2017), Office of the Superintendent of Financial Institutions. The 65% cap on the revolving portion and amortizing anything above it.
- Preparing for a mortgage, Financial Consumer Agency of Canada. The stress test for refinancing and HELOCs.
- Minimum qualifying rate for uninsured mortgages, Office of the Superintendent of Financial Institutions. The greater of the contract rate plus 2% or 5.25%.
- Policy interest rate, Bank of Canada. 2.50% from October 28, 2026; next decision December 9, 2026.
More Loans & Mortgages
Every tool in the Loans & Mortgages section, free and in your browser.