
Dollar to Peso Rates: Remittances, Markups and Card Fees
Why the dollar to peso rate online, at the remittance center and on your card differ, how to measure the markup in pesos, and why Gulf currencies are missing.
By Redbison Dev · · 7 min read
Philippines edition. Philippine edition in pesos, built on padala from the US, Singapore, Japan and Hong Kong, card spending on trips abroad, the BSP's Reference Exchange Rate Bulletin and ECB timings in Philippine time. US edition
The dollar to peso rate on a search page, the rate a remittance center or e-wallet pays out and the rate on your card statement are three different numbers, and only the first is close to a neutral middle rate. On November 6, 2026 the European Central Bank's reference rates gave 1 USD = ₱63.0166, so a US$500 padala was worth ₱31,508.28. A remittance center paying ₱62.50 per dollar would hand over ₱31,250, which is ₱258.28 less, a 0.82% markup that is never labeled as a fee. Knowing how to measure that gap in pesos is what an exchange rate tool is really for.
This edition works through it in pesos with the Currency Converter to Philippine Pesos. The international version of this article is here.
Where the converter's rates come from
The converter uses the ECB's euro foreign exchange reference rates, which include the Philippine peso. The ECB fixes them once each working day around 14:10 CET and publishes them at about 16:00 CET. In Philippine time that is about 11:00 pm in the European winter and 10:00 pm in the European summer, so a rate you check in Manila in the morning is the previous working day's. There are no rates on weekends or TARGET holidays such as December 25 and May 1.
The ECB says the rates are for information only and strongly discourages using them for transactions. They are a dated middle rate to measure quotes against, not a price anyone will pay you.
The BSP rate is a different series
The Bangko Sentral ng Pilipinas publishes its own Daily Reference Exchange Rate Bulletin (RERB) with daily peso-dollar data. The ECB and BSP figures come from different procedures at different times of day, so they can differ slightly. When a form, contract or government document asks for the BSP reference rate, use the BSP bulletin, not this converter.
How a dollar to peso rate is built
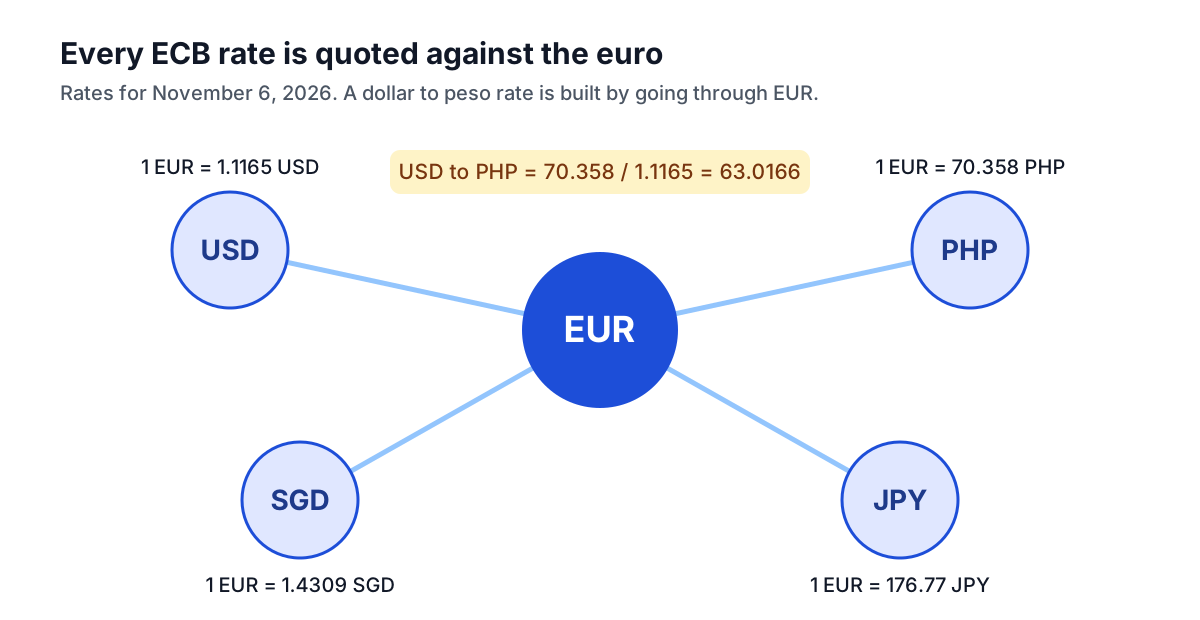
Every ECB rate is quoted against the euro, so USD to PHP is worked through the euro:
USD → PHP = (EUR → PHP) ÷ (EUR → USD)
          = 70.358 ÷ 1.1165
          = 63.0166
The same day's table gives the currencies many Filipino families receive:
| Sent in | 1 unit in pesos | Example |
|---|---|---|
| US dollar | ₱63.0166 | US$500 = ₱31,508.28 |
| Singapore dollar | ₱49.1705 | S$1,500 = ₱73,755.68 |
| Hong Kong dollar | ₱8.0405 | HK$5,000 = ₱40,202.27 |
| Japanese yen | ₱0.3980 | ¥100,000 = ₱39,802.00 |
| Korean won | ₱0.0464 | ₩1,000,000 = ₱46,379.09 |
| Canadian dollar | ₱44.7997 | C$2,000 = ₱89,599.49 |
Rates built from rounded euro quotes can differ from another site's in the last digit; that is rounding, not a different market.
The Gulf gap
The ECB does not publish rates for the Saudi riyal, UAE dirham, Qatari riyal or Kuwaiti dinar, so the converter cannot convert them. For a padala from the Middle East, compare remittance companies on the pesos credited for the same amount sent, or convert from US dollars if that is how the sender pays.
Measuring a remittance markup in pesos
Compare the rate you are offered with the reference rate:
markup = (reference rate − rate offered) ÷ reference rate
       = (63.0166 − 62.50) ÷ 63.0166
       = 0.82%
On US$500 that is ₱258.28. Fees change the picture. Suppose an app pays a better ₱62.90 per dollar but takes a US$3 fee from the amount sent, converting only US$497. The family receives ₱31,261.30, which is ₱246.98 short of the reference amount: only slightly better than the ₱62.50 center despite the fee. Put every option in the same terms, pesos received for the same amount sent, and the best one is clear.
Rates change during the day and between the time a transfer is sent and picked up, so compare quotes taken at the same moment and check which rate applies when the money actually converts.
Card spending on a trip abroad
On a trip to Japan, a ¥20,000 restaurant bill is ₱7,960.40 at the reference rate. Your card network converts it and the issuer usually adds a foreign transaction fee; check your card's schedule of fees for the percentage.
Pay in yen or in pesos?
A terminal may offer to charge you in pesos instead of yen. That is dynamic currency conversion (DCC), and the merchant's provider sets the rate. If it offers ₱8,400 for the ¥20,000 bill, that is 5.52% above the reference rate, usually more than paying in yen and letting your own card convert. Check it on the spot with the converter before you choose.
Pesos going out
Swap the direction to see what a peso budget buys abroad. ₱50,000 for school fees or a trip is about US$793.44 at the reference rate (1 PHP = 0.015869 USD). A bank selling you dollars charges more pesos per dollar than the reference rate, so expect to receive somewhat fewer dollars.
When the rate date matters
For a household budget, a day-old rate is fine. For anything someone will check later, an invoice to a foreign client, a reimbursement claim or a freelance contract paid in dollars, write the source and date into it, for example "converted at the ECB reference rate of November 6, 2026", or the BSP RERB rate if that is what the other party uses.
The converter's 30-day trend line shows whether today's rate is unusual compared with the past month. It is not a forecast. If you are converting a large amount, splitting it over several dates reduces the risk of converting all of it on a bad day.
A short checklist
- Note the rate's source and date: ECB or BSP, and which day.
- Compare remittance options on pesos received for the same amount sent, after fees.
- Decline DCC abroad unless its rate beats your card's.
- For riyals and dirhams, compare providers directly.
Tools for this job
- Currency Converter to Philippine Pesos: ECB reference rates into and out of pesos.
- Percentage Calculator: turns the gap between two rates into a markup percentage.
- Cryptocurrency Unit Converter: for units such as satoshi and gwei, which the ECB does not publish.
Frequently asked questions
Why does the remittance center pay a lower rate than Google?
Search pages and the ECB show a middle reference rate. Remittance companies, banks and e-wallets buy your dollars below it and keep the gap, and some charge a fee too. At ₱62.50 against a reference of ₱63.0166, the markup is 0.82%, ₱258.28 on US$500.
Is the ECB rate the same as the BSP reference rate?
No. The BSP publishes its own Daily Reference Exchange Rate Bulletin. The two are set by different procedures at different times, so they can differ slightly. Use the BSP bulletin when a document asks for it.
Should I pay in pesos or in the local currency abroad?
In the local currency, in most cases. Paying in pesos at the terminal is dynamic currency conversion, and a DCC price of ₱8,400 for a ¥20,000 bill is 5.52% above the reference rate.
Can I convert Saudi riyal or UAE dirham to pesos here?
No. The ECB does not publish those rates. Compare remittance companies on the pesos credited for the same amount sent.
Sources and further reading
- Reference Exchange Rate Bulletin, Bangko Sentral ng Pilipinas. Daily RERB and historical peso-dollar data.
- Euro foreign exchange reference rates, European Central Bank. Currencies covered, publication time, information-only status.
- ECB daily reference rates (XML), European Central Bank. The latest day's table, including PHP.
- Frankfurter: free exchange rate API, Frankfurter. Republishes the ECB rates and rebases them to any listed currency.
- lineofflight/frankfurter, Frankfurter project. The API's open-source code.
More Calculators
Every tool in the Calculators section, free and in your browser.
- Investment Calculator
- Compound Interest Calculator
- Simple Interest Calculator
- Interest Calculator
- EMI Calculator
- Retirement Calculator
- Time-Weighted Return Calculator
- Savings Goal Calculator
- Inflation Calculator
- CAGR Calculator
- ROI Calculator
- Present and Future Value Calculator
- NPV and IRR Calculator
- 401(k) Calculator
- Roth IRA Calculator
- APY and CD Calculator
- SIP Calculator
- Annuity Calculator
- Bond Price and Yield Calculator
- Currency Converter
- Dividend Calculator
- Stock Average Calculator
- RMD Calculator