
Loan Repayment in Naira: NHF Mortgages and Amortisation
How a monthly loan repayment splits into interest and principal in naira, worked on a 6% NHF mortgage, with tenor, prepayment, the one-third rule and flat rates.
By Redbison Dev · · 6 min read
Nigeria edition. Nigerian edition in naira, built on the National Housing Fund mortgage from the Federal Mortgage Bank of Nigeria (up to ₦50 million at 6% over up to 30 years), its one-third-of-income repayment limit, and flat-rate quotes on short consumer loans. US edition
On a ₦15 million National Housing Fund (NHF) mortgage at 6% over 20 years, the monthly repayment is ₦107,464.66. In the first month ₦75,000 of it is interest and only ₦32,464.66 reduces the loan. After five years of repayments you still owe ₦12.73 million, about 85% of what you borrowed, and over the full tenor the interest comes to ₦10.79 million. That shape is not peculiar to the NHF. Every fixed monthly repayment on a reducing balance, what Indian banks call an EMI, works the same way, and it decides how much a longer tenor, an early lump sum or a "flat" quote really costs you.
This edition works through the arithmetic in naira with the Loan and NHF Mortgage Repayment Calculator. The international version of this article is here. It explains how repayments work; it is not advice on any particular loan, and a mortgage is a commitment worth discussing with the primary mortgage bank and, if you can, an independent adviser.
The NHF mortgage in brief
The Federal Mortgage Bank of Nigeria (FMBN) runs the NHF loan through accredited primary mortgage banks (PMBs):
- A contributor can borrow up to ₦50 million, over a maximum tenor of 30 years.
- The Fund lends to PMBs at 4%, and PMBs lend on to contributors at 6%.
- You need six months of continuous contributions to the Fund, which is 2.5% of your monthly gross salary or income.
- FMBN uses no more than one-third of your monthly income to service the loan.
Commercial mortgages and personal loans in Nigeria are usually priced far above 6%, which is why the NHF route matters so much for salaried workers who qualify. The same arithmetic below works for any rate: type the one on your offer letter.
The repayment formula
A fixed monthly repayment that clears a loan exactly over n months is:
repayment = P × r × (1 + r)^n ÷ ((1 + r)^n − 1)

P = amount borrowed
r = monthly rate = yearly rate ÷ 12 ÷ 100
n = number of monthly repayments
For ₦15,000,000 at 6% over 240 months:
- r = 6 ÷ 12 ÷ 100 = 0.005.
- (1.005)^240 = 3.3102.
- Repayment = 15,000,000 × 0.005 × 3.3102 ÷ 2.3102 = ₦107,464.66.
Each month the PMB charges interest on what you still owe: month 1 is ₦15,000,000 × 0.005 = ₦75,000. The rest of the repayment, ₦32,464.66, reduces the balance, so month 2's interest is slightly smaller, and so on.
Where the money goes, year by year
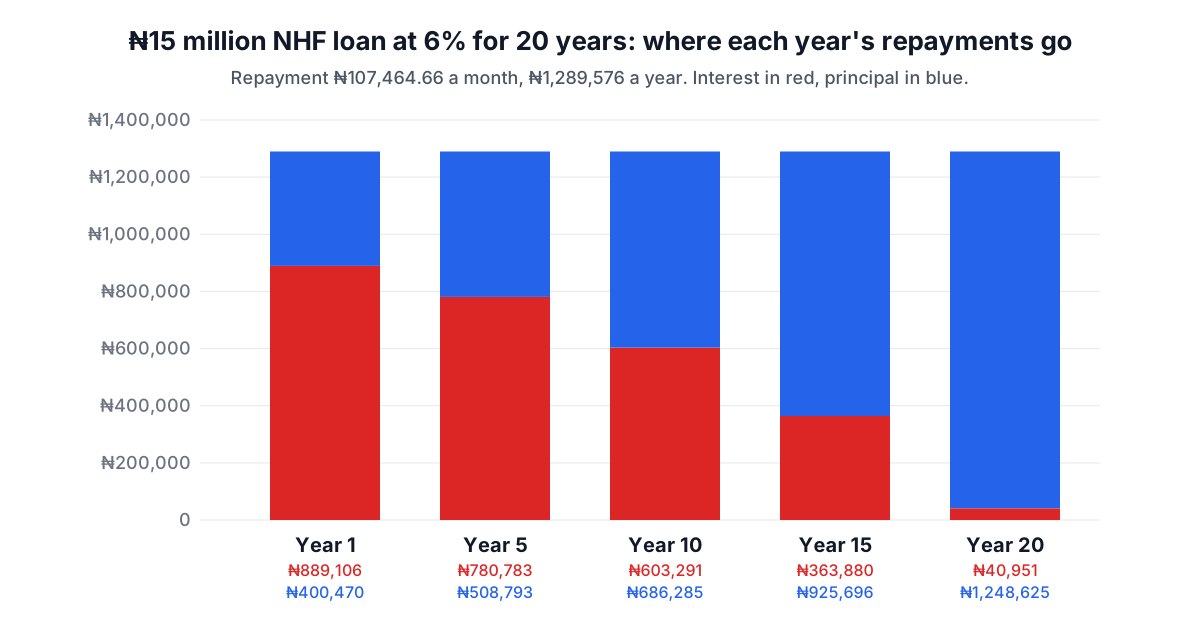
Every year of this loan you repay ₦1,289,575.92. How it splits:
| Year | Interest | Principal | Balance at year end |
|---|---|---|---|
| 1 | ₦889,106.08 | ₦400,469.82 | ₦14,599,530.18 |
| 5 | ₦780,783.34 | ₦508,792.57 | ₦12,734,939.77 |
| 10 | ₦603,290.97 | ₦686,284.94 | ₦9,679,712.93 |
| 15 | ₦363,880.37 | ₦925,695.54 | ₦5,558,669.74 |
| 20 | ₦40,951.34 | ₦1,248,624.57 | ₦0.00 |
Principal first overtakes interest at repayment 103, in the ninth year. If you expect to sell, relocate or refinance within a few years, the balance column is the figure to watch: after five years most of the loan is still outstanding.
The one-third rule decides what you can borrow
FMBN uses no more than a third of your monthly income to service an NHF loan, which it ties to the Labour Act's limit on salary deductions. So the income you need is three times the repayment:
| Loan | Rate | Tenor | Monthly repayment | Income needed | Total interest |
|---|---|---|---|---|---|
| ₦15 million | 6% | 30 years | ₦89,932.58 | ₦269,797.74 | ₦17,375,728.36 |
| ₦15 million | 6% | 20 years | ₦107,464.66 | ₦322,393.98 | ₦10,791,518.11 |
| ₦15 million | 6% | 10 years | ₦166,530.75 | ₦499,592.26 | ₦4,983,690.35 |
| ₦50 million | 6% | 30 years | ₦299,775.26 | ₦899,325.79 | ₦57,919,094.53 |
A longer tenor makes the loan fit a smaller salary, at the price of much more interest: going from 20 to 30 years cuts the repayment by ₦17,532 a month but adds ₦6.58 million in interest. In practice your age and retirement date may also limit the tenor, so ask the PMB what the longest tenor is for you.
The rate matters more than anything else
The same ₦15 million over 20 years at higher rates, for comparison with an offer outside the NHF:
| Rate | Monthly repayment | Total interest |
|---|---|---|
| 6% | ₦107,464.66 | ₦10,791,518.11 |
| 12% | ₦165,162.92 | ₦24,639,100.81 |
| 20% | ₦254,823.69 | ₦46,157,685.87 |
At 20% the interest is more than three times the loan, and the repayment would need ₦764,471 of monthly income under the one-third rule. These higher rates are illustrations, not quotes; put the rate from any real offer into the calculator.
Paying a lump sum early
Because interest is charged on the balance, any extra principal you pay stops costing interest for the rest of the loan. Suppose you pay ₦1,000,000 extra after the twelfth repayment, when the balance is ₦14,599,530.18. You can ask the PMB to do one of two things:
- Keep the repayment, shorten the tenor. The new balance of ₦13,599,530.18 at the same ₦107,464.66 or so is cleared in about 201 more repayments instead of 228, 27 fewer, and total interest falls by about ₦1.91 million.
- Keep the tenor, lower the repayment. Spread over the remaining 228 months, the repayment falls to ₦100,103.83, and total interest falls by about ₦678,000.
Shortening the tenor saves almost three times as much interest; lowering the repayment helps monthly cash flow. Ask the PMB whether part-prepayments are allowed, whether a charge applies and which option it will apply.
The flat-rate trap on short loans
Some consumer and car loans are quoted at a flat rate, where interest is charged on the original amount for the whole term even though you repay part of it every month. That makes a quote look far cheaper than the same figure on a reducing balance.
Take ₦500,000 at "5% a month flat" over six months:
- Interest: ₦500,000 × 5% × 6 = ₦150,000.
- Repayment: ₦650,000 ÷ 6 = ₦108,333.33 a month.
- The reducing-balance rate that gives the same ₦108,333.33 is about 8.05% a month, or 96.6% a year.
A car loan quoted at 24% a year flat over two years on ₦2 million works out to ₦123,333.33 a month and ₦960,000 of interest, equal to about 40.9% on a reducing balance. A true 24% reducing-balance loan would be ₦105,742.19 a month with ₦537,812.67 of interest.
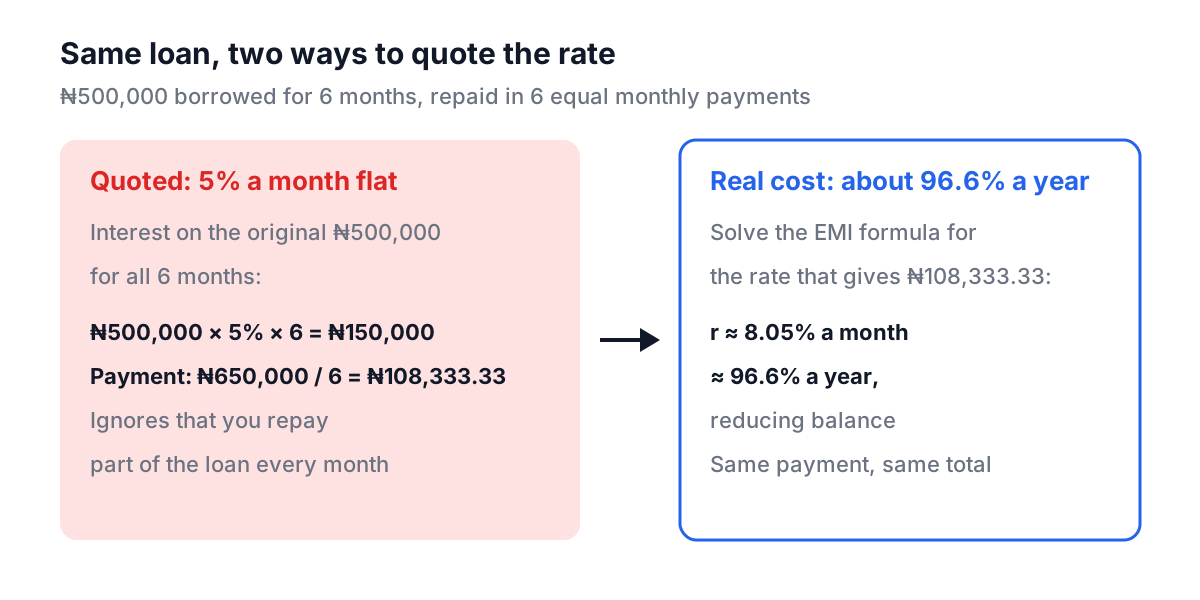
To compare a flat quote fairly, work out its repayment, then find the reducing rate that gives the same repayment: in the calculator, change the rate until the repayment matches. The Simple Interest Calculator gives the flat interest for the first step.
The rest of the monthly outgoing
The repayment covers interest and principal only. Estate service charges, insurance and other dues come on top. Enter them in the calculator's cost fields to see your total monthly outgoing; they do not change the interest figure, so you can still compare loans on loan cost alone.
Common mistakes
- Entering years in the months field. A 20-year tenor is 240 months.
- Comparing repayments, not totals. A lower repayment over a longer tenor almost always costs more.
- Treating a flat rate as a reducing rate. Convert first.
- Ignoring fees. Processing, legal and valuation fees raise the real cost even when the rate is unchanged.
- Expecting kobo-perfect agreement with the lender. Lenders round each repayment and may accrue interest daily, so small differences are normal.
Tools for this job
- Loan and NHF Mortgage Repayment Calculator: repayment, total interest and the full amortisation schedule in naira.
- Simple Interest Calculator: flat-rate interest, the first step in converting a flat quote.
- Rent vs Buy Calculator: whether owning beats renting once the repayment is known.
- The compound interest guide covers the other side of the ledger, savings that grow.
Frequently asked questions
What is the monthly repayment on a ₦15 million NHF loan?
At 6% over 20 years, ₦107,464.66 a month, with ₦10,791,518.11 of interest in total. Over 30 years it is ₦89,932.58 a month and ₦17,375,728.36 of interest. Under the one-third rule the 20-year loan needs a monthly income of about ₦322,394.
Why is most of my early repayment interest?
Interest is charged on the outstanding balance, which is largest at the start. On the ₦15 million loan, month 1 is ₦75,000 of interest out of ₦107,464.66, and principal only overtakes interest at repayment 103.
Is it better to shorten the tenor or reduce the repayment after a lump sum?
Shortening the tenor saves more interest. A ₦1 million prepayment after year one saves about ₦1.91 million if the tenor shortens, against about ₦678,000 if the repayment is reduced instead.
How do I compare a flat-rate loan with a reducing-balance loan?
Work out the flat loan's monthly repayment, then find the reducing rate that gives the same repayment. ₦500,000 at 5% a month flat over six months repays ₦108,333.33 a month, which is about 8.05% a month on a reducing balance.
Sources and further reading
- NHF Mortgage Loan, Federal Mortgage Bank of Nigeria. Up to ₦50 million at 6% over up to 30 years through an accredited PMB, after six months' contributions.
- NHF scheme: frequently asked questions, Federal Mortgage Bank of Nigeria. The one-third-of-income rule, the 2.5% contribution and refunds.
- Home Renovation Loan, Federal Mortgage Bank of Nigeria. NHF-funded loans to renovate or improve a home.
- 6.8 The Basics of Loans, OpenStax. The loan repayment formula and amortisation tables.
- 6.3 Simple Interest, OpenStax. The arithmetic behind a flat-rate quote.
More Calculators
Every tool in the Calculators section, free and in your browser.
- Investment Calculator
- Compound Interest Calculator
- Simple Interest Calculator
- Interest Calculator
- EMI Calculator
- Retirement Calculator
- Time-Weighted Return Calculator
- Savings Goal Calculator
- Inflation Calculator
- CAGR Calculator
- ROI Calculator
- Present and Future Value Calculator
- NPV and IRR Calculator
- 401(k) Calculator
- Roth IRA Calculator
- APY and CD Calculator
- SIP Calculator
- Annuity Calculator
- Bond Price and Yield Calculator
- Currency Converter
- Dividend Calculator
- Stock Average Calculator
- RMD Calculator